When buying a home in Burke, Springfield, or Fairfax, Virginia, comparing listing prices alone can lead to an incomplete budget. Two homes with similar asking prices can have different monthly costs because of mortgage terms, property taxes, homeowners insurance, HOA fees, utilities, and expected maintenance.
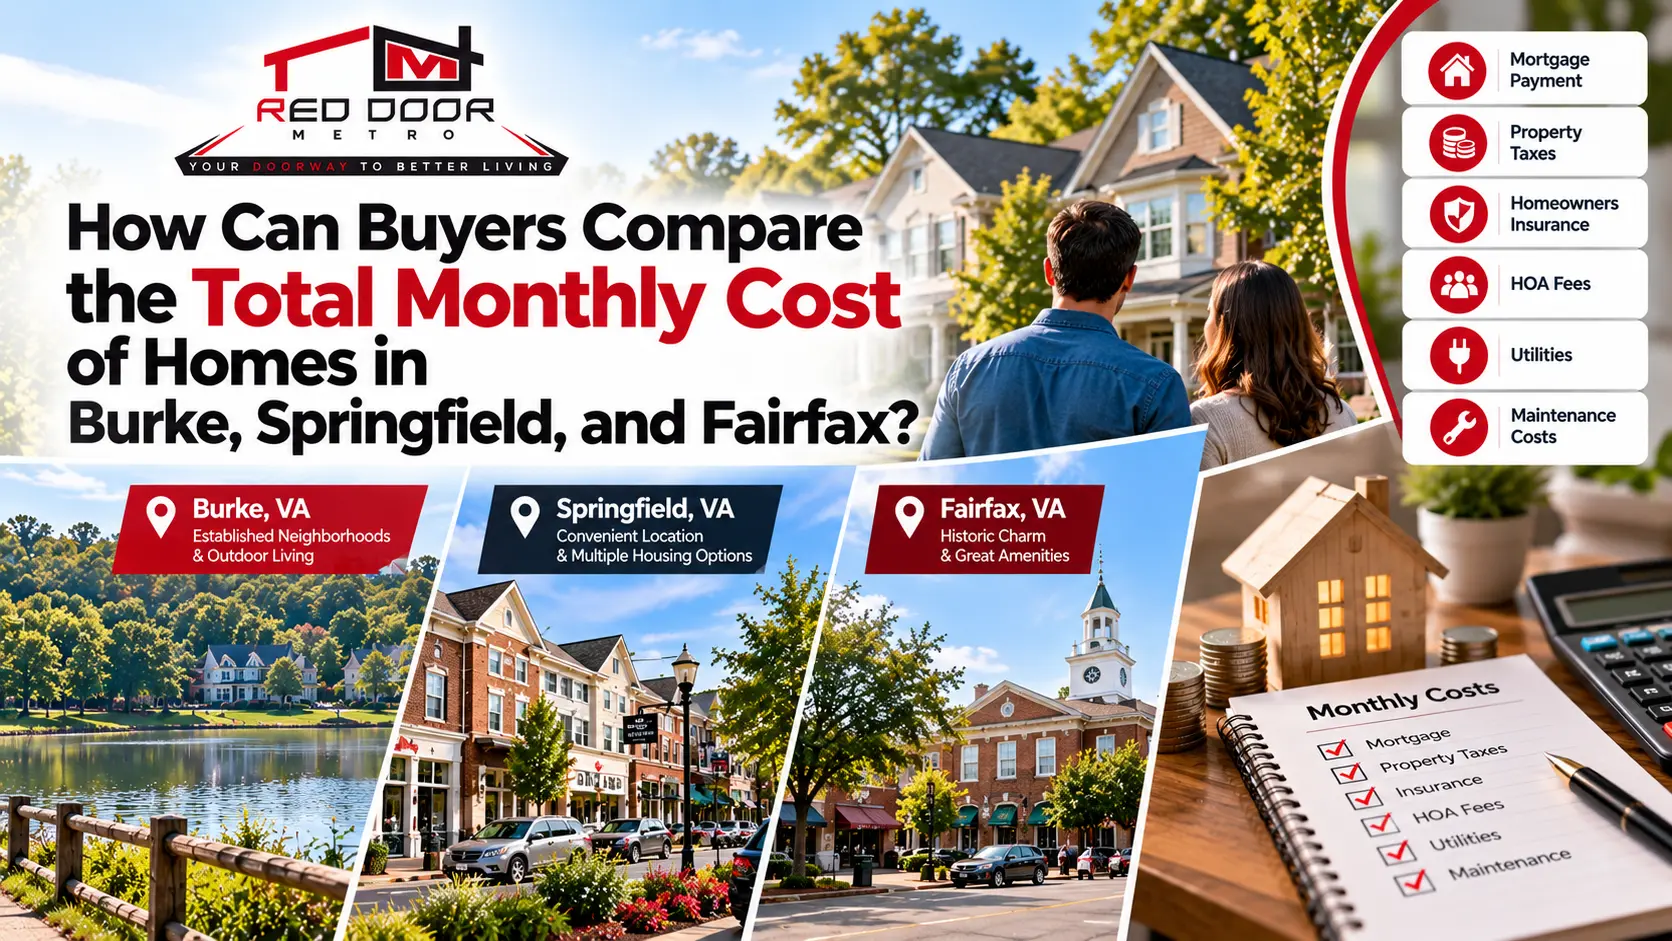
The best way to compare these Northern Virginia communities is to calculate the estimated monthly cost of owning each specific property. This approach helps buyers understand what fits their budget while weighing commute options, property features, neighborhood preferences, and long-term financial goals.
Quick Answer: How Should Buyers Compare Monthly Costs?
Compare the mortgage principal and interest, property taxes, homeowners insurance, mortgage insurance if applicable, HOA or condominium fees, utilities, and a monthly maintenance reserve. Use the same mortgage assumptions for each property, verify the actual tax jurisdiction, and request property-specific insurance and association estimates before deciding.
1. Compare the Total Cost, Not Just the Purchase Price
A home’s asking price is only the starting point. The total monthly ownership cost includes several expenses, and some may not appear in a standard mortgage payment estimate.
For each property in Burke, Springfield, or Fairfax, compare the following:
- Mortgage principal and interest: Based on the loan amount, interest rate, and repayment term.
- Property taxes: Based on the property’s assessed value and applicable local tax rates.
- Homeowners insurance: Based on the property’s characteristics, coverage, deductible, and insurer.
- Mortgage insurance: May apply depending on the loan program, down payment, and lender requirements.
- HOA or condominium fees: Applicable assessments and any additional association charges.
- Utilities: Electricity, gas, water, sewer, trash, and other services not included in association fees.
- Maintenance reserve: Money set aside for repairs, upkeep, and eventual replacement of major systems.
- Other property costs: For example, private road charges, applicable service fees, or special assessments.
Keep one-time expenses, such as closing costs and initial repairs, in a separate budget. They affect the cash needed to purchase a home but should not be confused with recurring monthly expenses.
2. Understand How Monthly Costs May Differ by Area
Burke, Springfield, and Fairfax offer a range of home styles and price points. However, the community name alone does not determine affordability. The specific home, its condition, its tax jurisdiction, and the financing terms can make a substantial difference.
Burke, VA
Buyers considering Burke should compare detached homes, townhouses, and condominiums based on their full monthly costs. Some properties may have association assessments, while others may have different exterior maintenance responsibilities. Buyers should also factor in commuting expenses and the condition of the roof, HVAC system, plumbing, and other major components.
If you are comparing homes in Burke Centre or another planned community, verify the current association fees and whether more than one assessment applies to the property.
Springfield, VA
Springfield includes a variety of residential neighborhoods and property types. Compare the purchase price with the home’s condition, expected maintenance, commute, and applicable property taxes.
A home with a lower asking price may not be the least expensive option over time if it needs major repairs or has higher insurance costs. Conversely, a property with a higher purchase price may offer features or a condition that better fit your household’s needs. Evaluate the actual numbers rather than relying on a general neighborhood average.
Fairfax, VA
When comparing Fairfax homes, first establish whether the property is in Fairfax County or the independent City of Fairfax. These are different tax jurisdictions, so buyers should verify the applicable tax rate and any additional charges for the exact property.
Also compare the home’s age, maintenance requirements, association fees, insurance quote, and transportation costs. A property located in one jurisdiction is not automatically more affordable than a comparable home in another.
3. Calculate the Mortgage Payment Consistently
Mortgage principal and interest are often the largest parts of the monthly housing budget. To make a fair comparison, use the same down payment percentage, interest rate, and loan term for each home. You can then compare the effect of the purchase price on the payment.
For a fixed-rate mortgage, the principal-and-interest payment depends on:
- The purchase price and down payment.
- The amount borrowed after the down payment.
- The mortgage interest rate.
- The loan term, such as 15 or 30 years.
Do not assume that an advertised mortgage rate will be available to every buyer. Actual rates and loan costs depend on the lender, credit profile, loan program, points, and other factors. Ask a lender for comparable estimates based on your circumstances.
Also remember that principal and interest are not the complete mortgage-related housing cost. Property taxes, insurance, mortgage insurance when applicable, and association fees may be billed separately or collected through an escrow account.
4. Compare Property Taxes Carefully
Property taxes can materially affect monthly affordability in Northern Virginia. The tax amount is generally calculated using the property’s assessed value and the tax rates that apply to its location.
Fairfax County’s published 2026 base real estate tax rate is $1.12 per $100 of assessed value. Certain properties may have additional district taxes or fees, so the base rate should not automatically be treated as the final rate for every parcel.
Illustrative Property Tax Calculation
Assessed value: $700,000
Example base rate: $1.12 per $100
Estimated annual tax at that base rate: $7,840
Monthly equivalent: approximately $653.33
This is an illustration using the county base rate, not a tax quote for a specific home. Applicable district charges and the actual assessed value can change the final bill.
Before making an offer, verify the current assessment and applicable tax rates for the property. Do not rely exclusively on a listing’s historical tax figure because assessments, tax rates, and owner-specific relief can affect what you will pay.
Official information is available through the Fairfax County real estate tax rate page and the City of Fairfax real estate tax page.
5. Include Homeowners Insurance and Mortgage Insurance
Homeowners insurance is another recurring expense that buyers should estimate before committing to a property. Premiums can vary based on replacement cost, property age, roof condition, claims history, coverage limits, deductible, and insurer.
Request a quote for each home you are seriously considering. Using one statewide average for every property can produce a misleading comparison.
Mortgage insurance may also apply when the down payment or loan structure requires it. Its cost and cancellation rules depend on the loan program and lender. Ask your lender to include any applicable mortgage insurance in the monthly estimate.
For properties governed by a condominium association, review the association’s master insurance coverage and determine what your individual policy must cover. Do not assume the association’s policy replaces all personal homeowners insurance needs.
6. Add HOA Fees and Other Association Charges
Association fees can affect the comparison between a detached home, townhouse, and condominium. Some associations provide services or maintain common areas that individual owners would otherwise manage themselves. Others may have separate charges or restrictions that buyers should understand before closing.
For each property, verify:
- The current regular assessment and payment frequency.
- Whether a second association or condominium fee applies.
- What services and amenities the fee covers.
- Whether a special assessment has been approved or proposed.
- Whether the association has announced an increase.
- Which maintenance responsibilities remain with the homeowner.
Convert quarterly or annual assessments into monthly amounts when comparing homes. Review the relevant association documents and resale certificate rather than relying solely on the amount shown in an old listing.
7. Budget for Utilities and Maintenance
Utility costs can differ depending on the size of the home, insulation, heating and cooling systems, household occupancy, and personal usage. Ask the seller for recent utility information where available, and remember that a previous owner’s consumption may differ from yours.
Maintenance deserves equal attention. A home with an aging roof, older HVAC equipment, deteriorating windows, or drainage issues may require more spending than a recently updated property.
Before making a decision:
- Review the home inspection findings and recommendations.
- Ask about the age and service history of major systems.
- Obtain specialist evaluations where the general inspection identifies concerns.
- Estimate near-term repairs separately from routine maintenance.
- Set aside a recurring reserve for future work, even if the home appears to be in good condition.
A maintenance reserve is a planning estimate, not a bill that every homeowner will pay each month. Its purpose is to prevent predictable long-term expenses from becoming financial surprises.
8. Use a Side-by-Side Monthly Cost Comparison
Build one comparison sheet for a home in Burke, one in Springfield, and one in Fairfax. Enter verified figures for each property instead of using broad citywide assumptions.
| Monthly expense | Burke home | Springfield home | Fairfax home |
|---|---|---|---|
| Mortgage principal and interest | $_____ | $_____ | $_____ |
| Property taxes ÷ 12 | $_____ | $_____ | $_____ |
| Homeowners insurance ÷ 12 | $_____ | $_____ | $_____ |
| Mortgage insurance, if applicable | $_____ | $_____ | $_____ |
| HOA or condo fees | $_____ | $_____ | $_____ |
| Utilities | $_____ | $_____ | $_____ |
| Maintenance reserve | $_____ | $_____ | $_____ |
| Estimated monthly total | $_____ | $_____ | $_____ |
Add any other recurring property charges that apply. If you want to compare commuting costs, keep those in a separate line so you can distinguish the cost of owning the home from the cost of getting to work.
9. Consider the Commute and Your Daily Lifestyle
The least expensive property on a monthly ownership worksheet may not be the best fit for every household. Transportation, time, convenience, and the home’s features also matter.
When comparing Burke, Springfield, and Fairfax, consider:
- Travel time to your workplace during your normal commuting hours.
- Access to VRE, Metro, major roads, or local bus service where relevant.
- Parking costs, tolls, fuel, and transit fares.
- Distance to shopping, medical services, recreation, and other regular destinations.
- Space and layout for your current household and future plans.
- Maintenance responsibilities and the time required to manage the property.
For example, a property with a slightly higher housing cost might reduce commuting expenses or better meet your family’s needs. Calculate both the housing budget and the wider household budget before making a decision.
10. Avoid Common Home Affordability Mistakes
Buyers can underestimate monthly expenses when they focus only on the advertised mortgage payment. Avoid these common errors:
- Using the list price as the entire budget: Taxes, insurance, utilities, and upkeep can add substantial costs.
- Assuming the tax bill will stay unchanged: Assessments, rates, and applicable charges may change.
- Using a generic insurance estimate: Request a quote for the actual property and required coverage.
- Ignoring association documents: Regular dues may not reveal special assessments or future increases.
- Underestimating repairs: Review inspection findings and the age of major systems.
- Forgetting one-time cash needs: Closing costs, moving expenses, and immediate repairs should be budgeted separately.
- Spending to the lender’s maximum: Loan approval does not necessarily mean the payment is comfortable for your household.
Frequently Asked Questions
Is Burke, Springfield, or Fairfax the cheapest place to buy a home?
There is no universal answer. Total cost depends on the specific property’s price, loan terms, tax jurisdiction, insurance quote, association fees, utilities, and maintenance needs. Compare actual homes using the same assumptions before deciding.
What is included in the total monthly cost of homeownership?
Include mortgage principal and interest, property taxes, homeowners insurance, mortgage insurance when applicable, HOA or condominium fees, utilities, and a maintenance reserve. Add other recurring charges that apply to the property.
Are property taxes the same in Burke, Springfield, and Fairfax?
Not necessarily. Burke and Springfield properties generally use Fairfax County’s tax system, but applicable district charges can vary. Fairfax can refer to either Fairfax County or the independent City of Fairfax, which has its own tax system. Verify the property’s exact jurisdiction and tax details.
Should HOA fees be included when comparing homes?
Yes. Include the current assessment and any other applicable association charges. Review the association’s documents for services covered, special assessments, and possible fee increases.
How much should I set aside for home maintenance?
There is no single reserve amount that fits every home. Consider the property’s age, condition, size, systems, and inspection findings. A qualified inspector can help identify likely near-term repairs, while your budget should also allow for unexpected expenses.
Should I compare homes using the same mortgage rate?
For an initial comparison, using the same rate, down payment percentage, and loan term helps isolate differences in purchase price and recurring expenses. Before purchasing, replace those assumptions with a lender’s estimate based on your actual loan options.
Final Takeaway: Compare the Full Monthly Budget
When comparing homes in Burke, Springfield, and Fairfax, the most useful number is not the asking price or mortgage payment alone. It is the estimated total cost of owning the property each month, supported by current tax information, an insurance quote, association documents, and a realistic maintenance budget.
Use the same comparison method for every property, verify whether a Fairfax address is in the county or the independent city, and keep commuting and one-time purchase expenses visible in your overall budget. This gives you a clearer basis for deciding which home fits your finances and lifestyle.
Comparing Homes Across Northern Virginia?
Red Door Metro helps buyers explore properties across Northern Virginia and the wider DMV. Search available homes and discuss your priorities before narrowing your choices.
Red Door Metro · Your Doorway to Better Living